Compulsory Earthquake Insurance (DASK) in Turkey: What It Covers and How to Renew It

In short
DASK is the compulsory earthquake insurance for residential buildings in Turkey, administered by the Natural Disaster Insurance Institution. It is required when ownership is transferred at the land registry and when opening water and electricity subscriptions, and it is renewed every year. It covers damage to the building itself from an earthquake and its consequences up to a set compensation limit, but not furniture and contents, which is why optional home insurance is often added.
Written by Abdulhadi Uçkun, Founder & owner
Last reviewed October 7, 2026
When preparing the land registry paperwork, buyers often ask about the “DASK” item on the list: what is it, and why can't the sale go through without it? The answer is that it is the compulsory earthquake insurance, part of the system Turkey built after the 1999 earthquake to spread the cost of reconstruction.
What is DASK?
The acronym of the Natural Disaster Insurance Institution (Doğal Afet Sigortaları Kurumu), a public body that administers “compulsory earthquake insurance”. It is bought from insurance companies, agents and banks, but the terms and prices are set by a single unified system.
Who must have it?
Residential buildings registered at the land registry within municipal boundaries, which includes almost every apartment we offer. In practice it is required in two places:
- At the land registry: ownership of a residential property cannot be transferred without a valid policy. See the land registry day guide.
- For utility subscriptions: water and electricity companies ask for the policy when opening a new subscription in your name.
What does it cover?
- Damage to the building itself caused by an earthquake.
- Damage from fire, explosion, landslide or tsunami caused by the earthquake.
This is up to a maximum compensation limit that is updated periodically and calculated according to the area and type of construction.
And what does it not cover?
- Furniture, appliances and contents.
- Damage exceeding the compensation limit in large or luxury apartments.
- Personal injury and loss of income.
That is why many owners add optional home insurance (Konut Sigortası) covering the contents and anything beyond the DASK limit, as well as other risks such as ordinary fire, theft and water leaks.
How is the price calculated?
The cost of the policy depends on three factors:
- Type of construction: reinforced concrete, steel frame, masonry or other.
- The area's earthquake risk level: Istanbul is higher risk than most of Trabzon's coast, so premiums there are usually higher. We explain the difference in the earthquake building safety guide.
- The apartment's gross area.
Annual renewal
The policy is annual. Set a reminder before its expiry date, or ask your bank or insurer for automatic renewal. If you are outside Turkey most of the year, you can renew it online with your tax number or foreigner ID number.
If an earthquake strikes
Report the damage to DASK through its official channels as soon as possible, and keep photos of the damage and your policy number. An assessor is sent to estimate the damage, and compensation is set within the policy limits.
In short
DASK is a legal requirement for transferring ownership and opening subscriptions, and it is relatively cheap, but it covers only the building and only up to a certain limit. Renew it every year, and consider home insurance to complement it if your apartment is furnished or of high value. You will find all of an owner's annual expenses in the costs and taxes guide.
We arrange the DASK policy for our clients as part of preparing the land registry paperwork, and remind them to renew it. Contact us.
Sources
Related guides

Mortgages for foreigners in Turkey: are they possible, and do they make sense?
Some Turkish banks lend to foreigners for property purchases, but on stricter terms than for citizens, usually requiring residence, documented income and a large down payment. Since its decision of 29 January 2026, the banking regulator has set loan-to-value caps that fall as the property price rises, and it has removed the distinction between new and resale homes. Home loans to individuals in Turkey are usually in Turkish lira and carry high interest rates, which is why most foreigners buy in cash or through developer instalment plans.
Last reviewed Oct 7, 2026

Developer instalment plans in Turkey: how to read the offer and protect your payments
Many developers in Turkey offer a down payment (often between a third and a half of the price) followed by monthly or quarterly instalments until handover, and sometimes after it. Instalments usually carry no stated interest, but the cash price is normally lower, so compare the two. What matters most is where your rights stand while you pay: a title deed in your name with a mortgage in the developer’s favour, or a notarised promise-of-sale contract registered as a şerh (annotation) at the tapu (land registry), not just a private contract.
Last reviewed Oct 7, 2026

The declared value on the tapu: why registering a lower price saves you nothing
The tapu (title deed) fee is 4% of the declared value (legally 2% for each party), and the base cannot be lower than the property-tax value held by the municipality. In a sale to a foreigner, the declared price cannot be lower than the value in the mandatory valuation report. Registering a price below the real one breaks the law and exposes you to fines, raises your capital gains tax if you sell within five years, and may cost you the value requirement for residence or citizenship. Declare the real price.
Last reviewed Oct 7, 2026
Related areas

Related listings
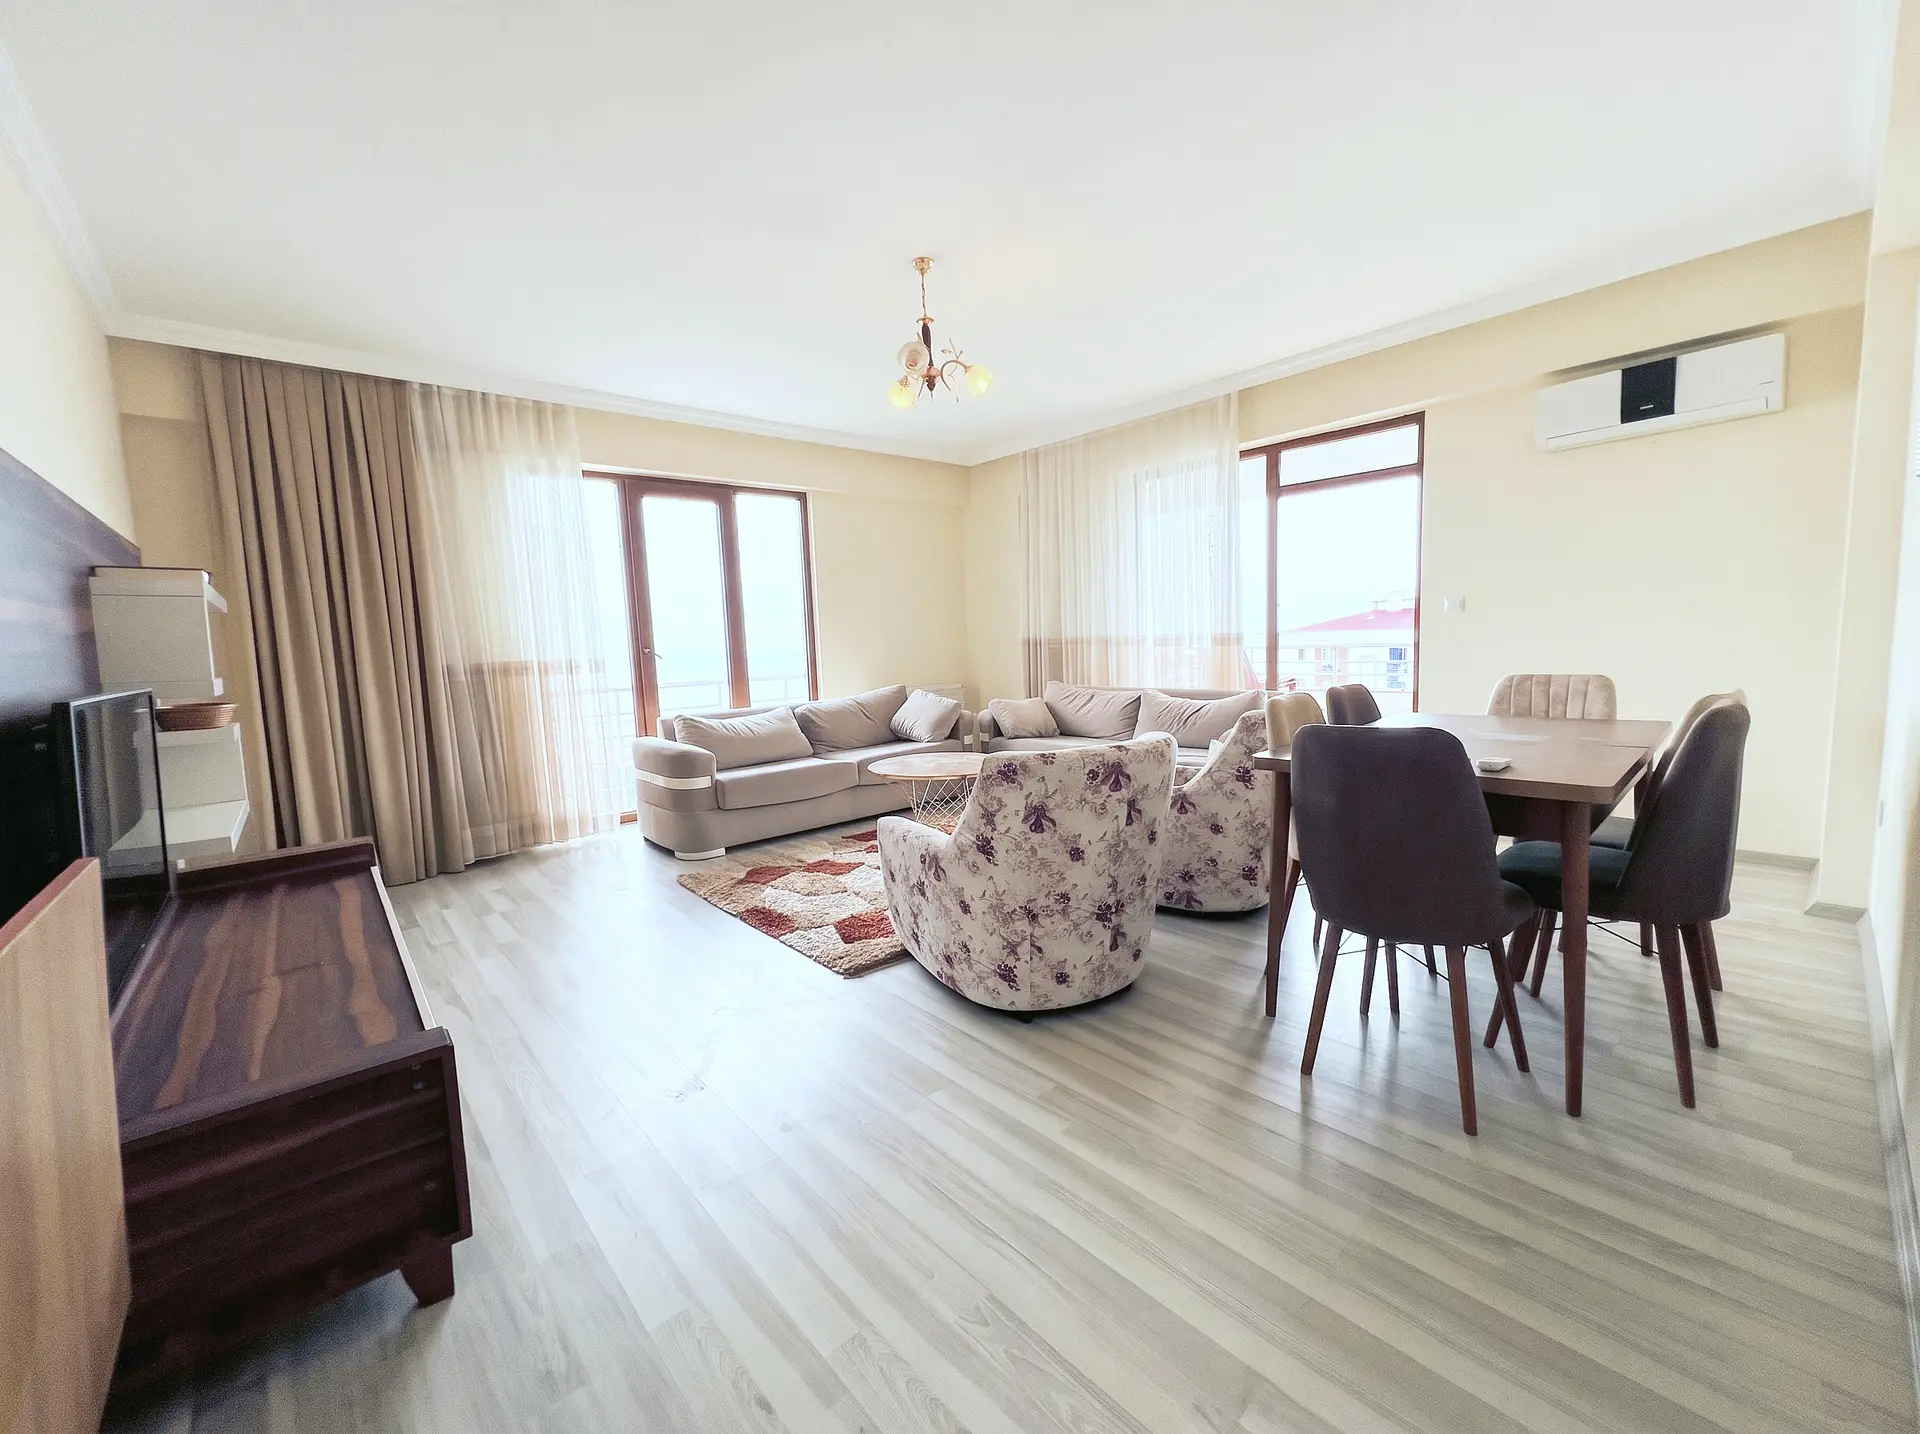 Fully furnishedBRJ-1119
$140,000
Furnished 4+1 family apartment with sea view near the airport, Pelitli
- 4+1
- 180 m²
- Pelitli, Trabzon
SeaForest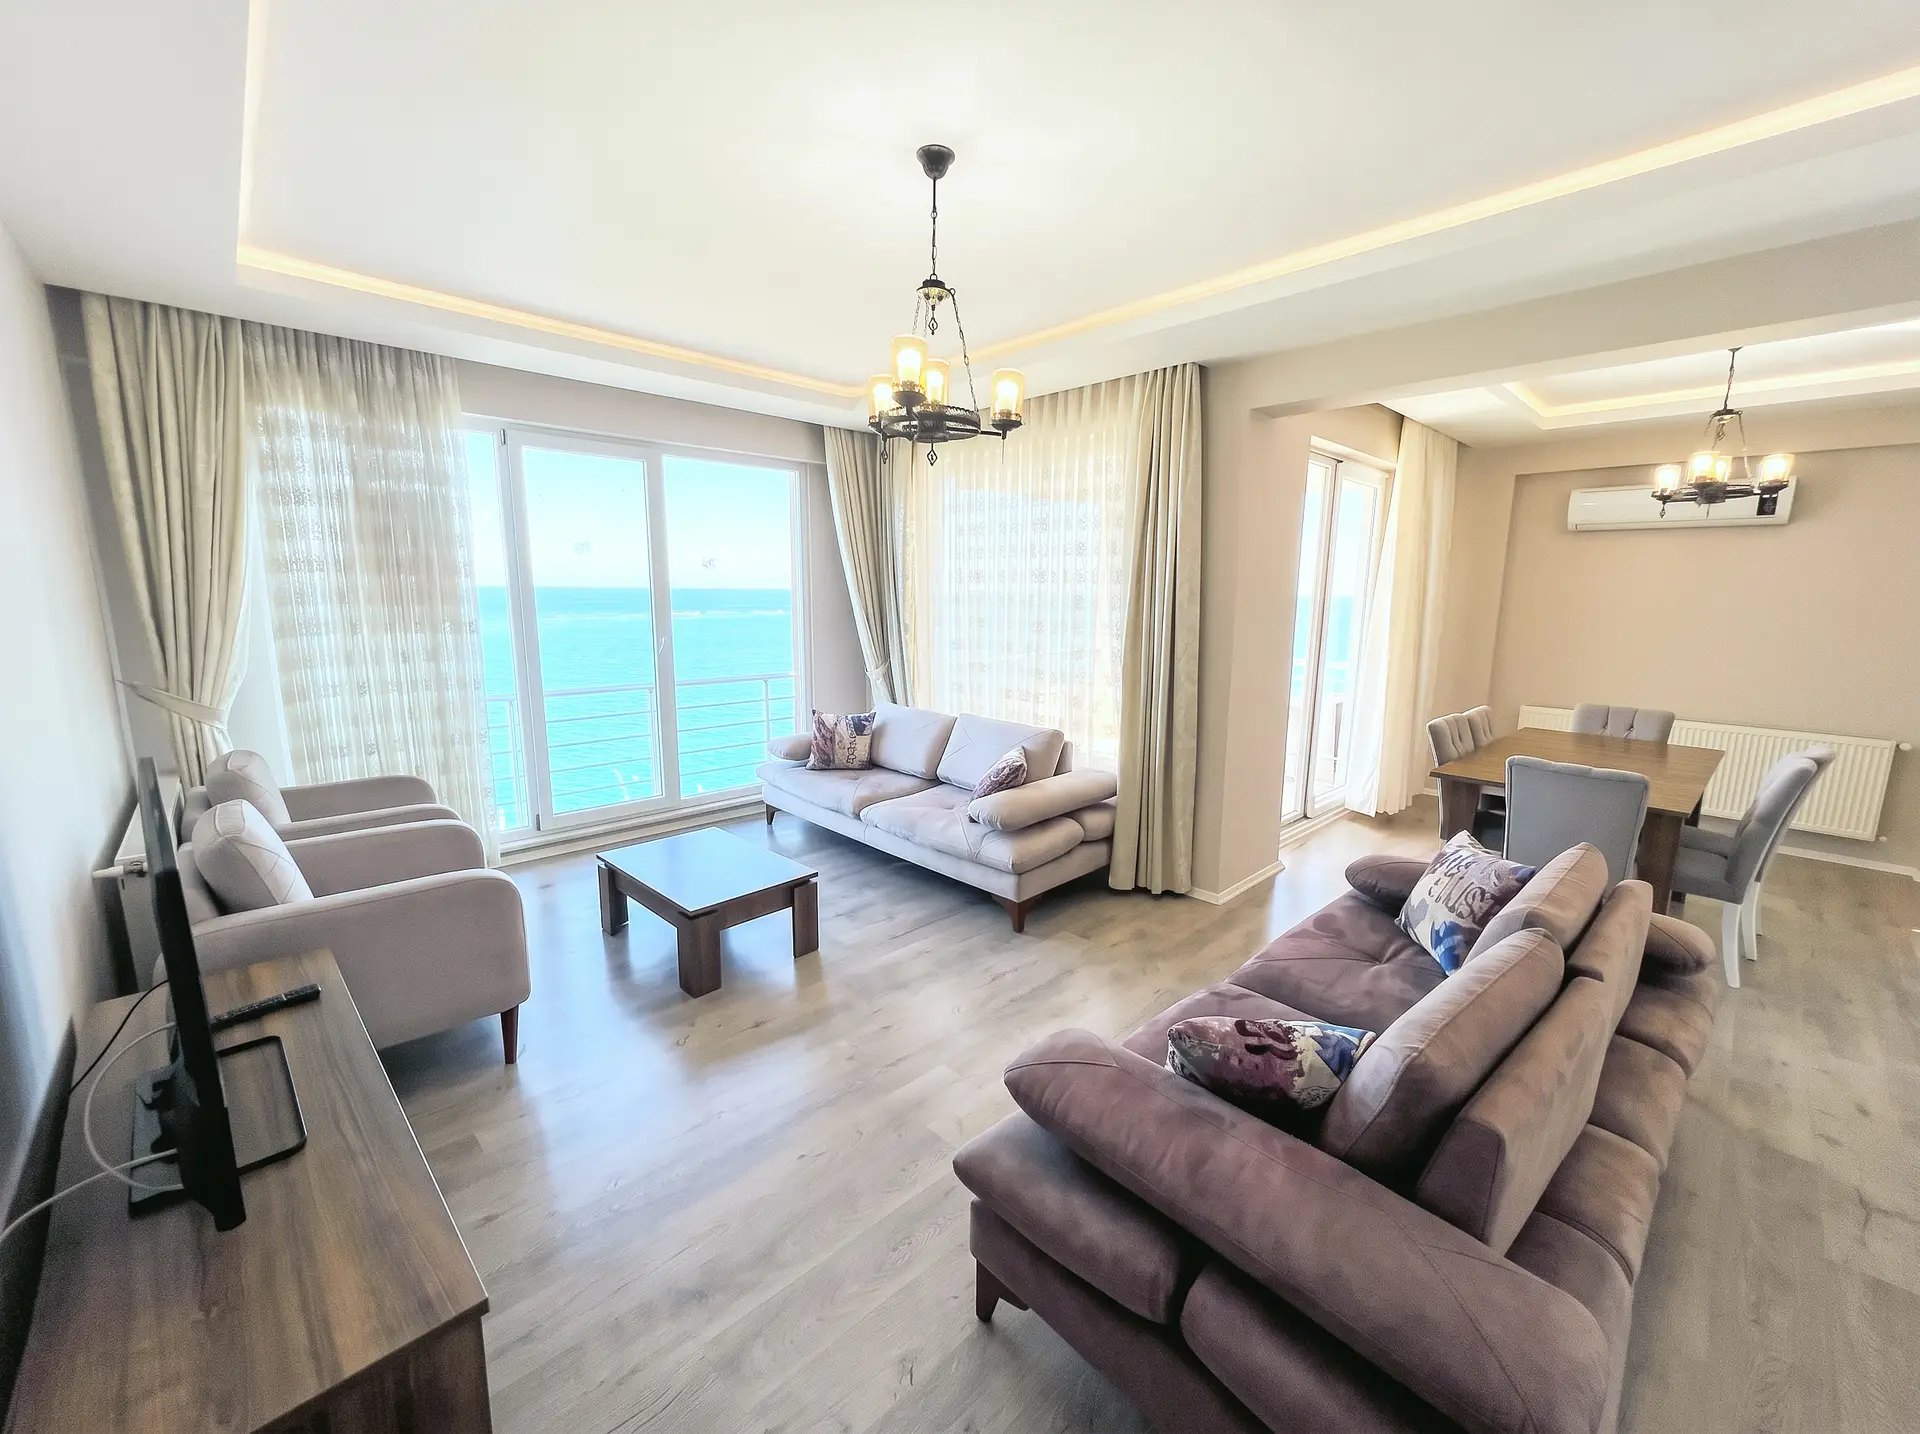 Fully furnishedBRJ-1118
$153,000
Furnished 3+1 apartment with direct sea view, Mersin, Akçaabat
- 3+1
- 150 m²
- Mersin, Trabzon
Sea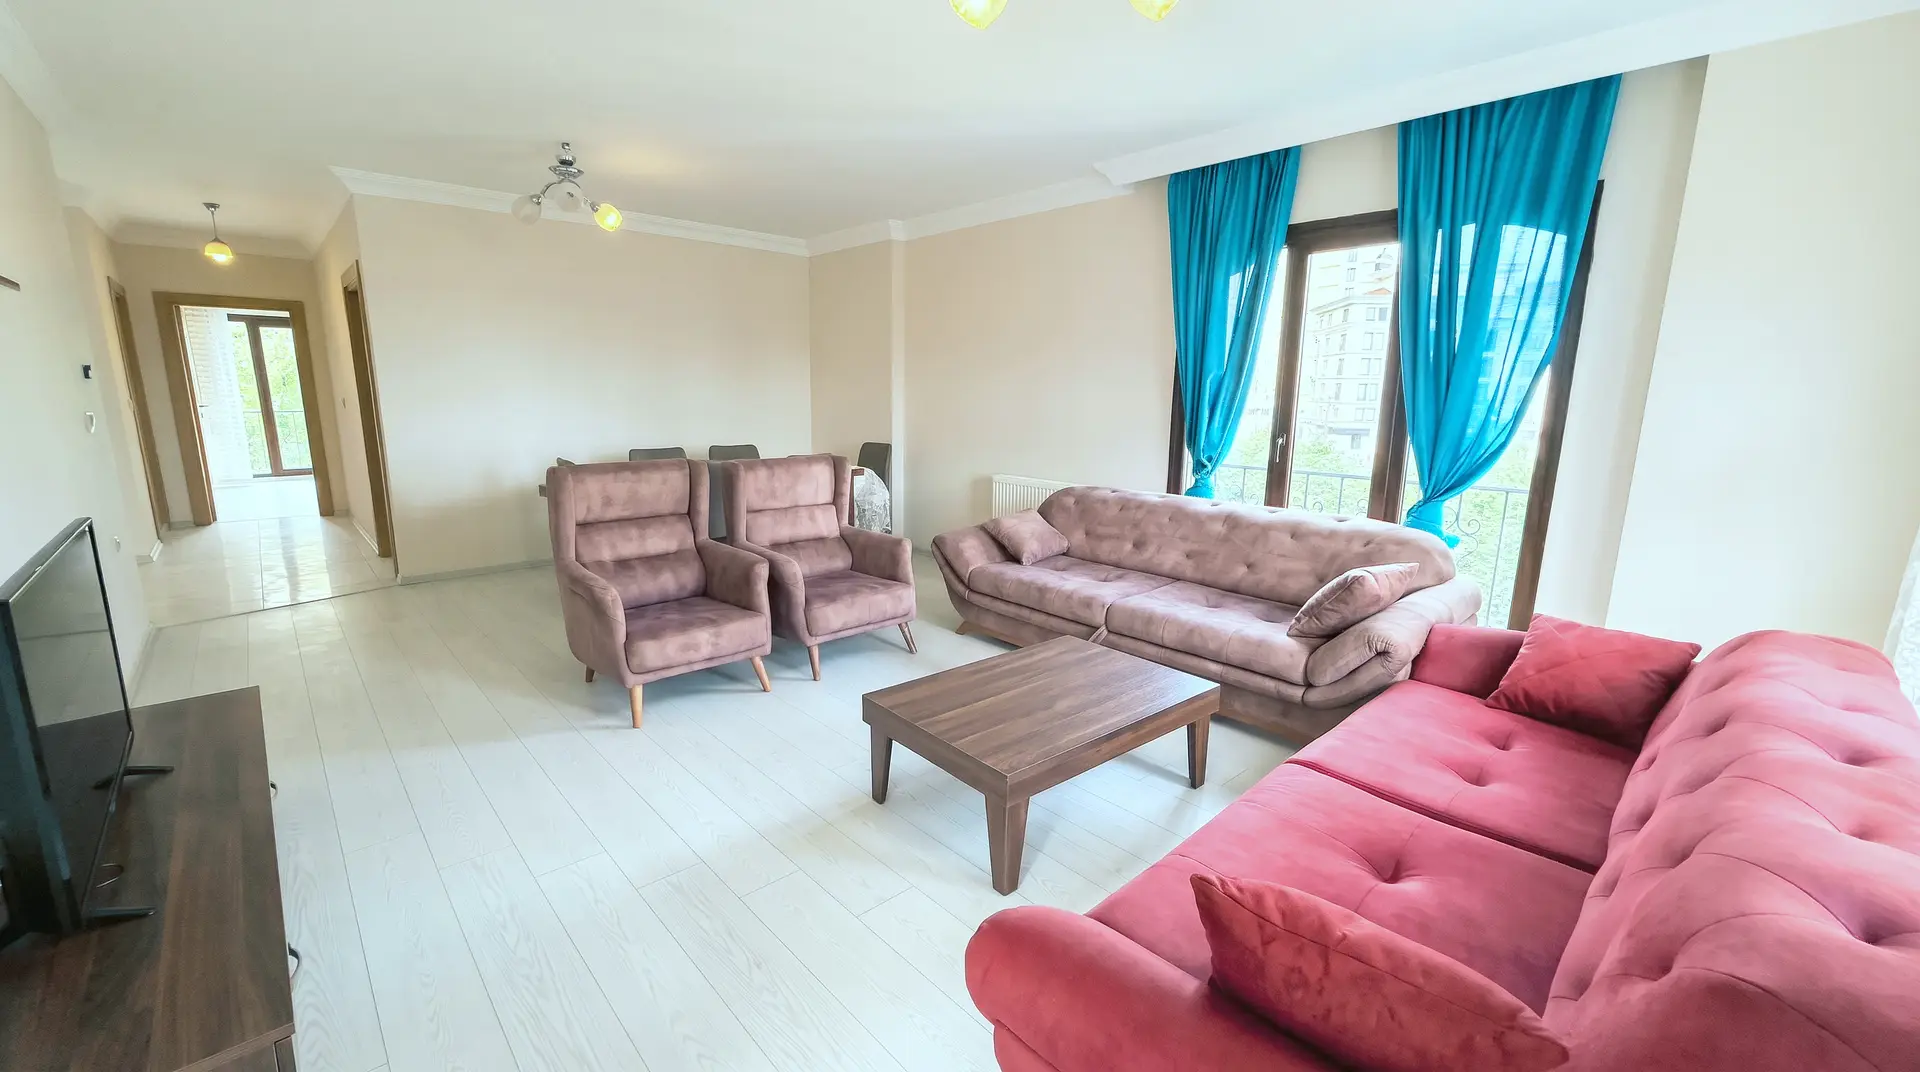 Fully furnishedBRJ-1117
$125,000
Furnished 3+1 apartment with a very large balcony and sea view, Pelitli
- 3+1
- 176 m²
- Pelitli, Trabzon
SeaForest